
What Can a Reverse Mortgage Help You Do?
A reverse mortgage can turn a portion of your home equity into a financial resource while allowing you to continue owning and living in your home.
Eliminate Required Monthly Mortgage Payments
Pay off an existing mortgage and eliminate required monthly principal and interest payments, while continuing to own and live in your home.*
Create Greater Financial Flexibility
Use home equity to supplement retirement income, manage unexpected expenses, make home improvements, or preserve other assets.
Access Your Home Equity
Receive available proceeds as a lump sum, monthly advances, a line of credit, or a combination—depending on the reverse mortgage program.
Purchase Your Next Home
A reverse mortgage can also help eligible homeowners purchase another home while reducing the amount of cash they need to commit to the purchase.
*Borrowers remain responsible for property taxes, homeowners insurance, property maintenance, and other applicable property charges.
How a Reverse Mortgage Works
A reverse mortgage allows eligible homeowners to borrow against a portion of their home equity without requiring monthly principal and interest payments.*
You Continue to Own Your Home
You retain title to your home and continue living there, just as you do with a traditional mortgage.
You Remain Responsible for the Home
You continue to be responsible for property taxes, homeowners insurance, property maintenance, and other applicable property charges.
The Loan Balance Changes Over Time
Because monthly principal and interest payments are not required, interest and applicable loan charges are generally added to the loan balance over time.
The Loan Is Repaid Later
The loan generally becomes due when the last borrower permanently leaves the home, sells the home, or another repayment event occurs under the loan terms.
Do I Qualify for a Reverse Mortgage?
Eligibility depends on several factors, including your age, the property, the amount of equity available, and your ability to meet the ongoing obligations of the loan.
Age Requirements
For an FHA-insured HECM, the youngest borrower must generally be at least 62. Some proprietary reverse mortgage programs may be available to eligible homeowners beginning at age 55.
Sufficient Home Equity
The amount available depends on factors such as your age, home value, existing mortgage balance, interest rates, and the reverse mortgage program selected.
Property Requirements
The home generally must be your principal residence and meet the property and program requirements for the reverse mortgage you choose.
Ability to Meet Ongoing Obligations
You must demonstrate the ability to meet ongoing property obligations, including property taxes, homeowners insurance, maintenance, and other applicable property charges.
What Happens to My Home and Equity Later?
A reverse mortgage doesn’t mean giving up ownership of your home. You remain the owner, and when the loan eventually becomes due, you or your heirs generally have options for deciding what happens next.
When the Loan Becomes Due
The loan generally becomes due when the last borrower permanently leaves the home, sells the home, or another repayment event occurs under the loan terms.
Your Heirs Have Options
When the loan becomes due, the home can generally be sold to repay the loan, or your heirs may choose to keep the home by repaying or refinancing the amount required under the loan terms. Any remaining equity belongs to you or your estate.
You Won’t Owe More Than the Home Is Worth
For an FHA-insured HECM, the loan is non-recourse. When the loan becomes due, you or your heirs generally will not be required to repay more than the home’s value, even if the loan balance is higher.
Purchase Your Next Home With a Reverse Mortgage
A reverse mortgage isn't only a way to access equity in the home you already own. For eligible homeowners, it may also be used to purchase a new principal residence.
This can be especially useful if you're considering downsizing, moving closer to family, relocating for retirement, or simply choosing a home that better fits the next chapter of your life.
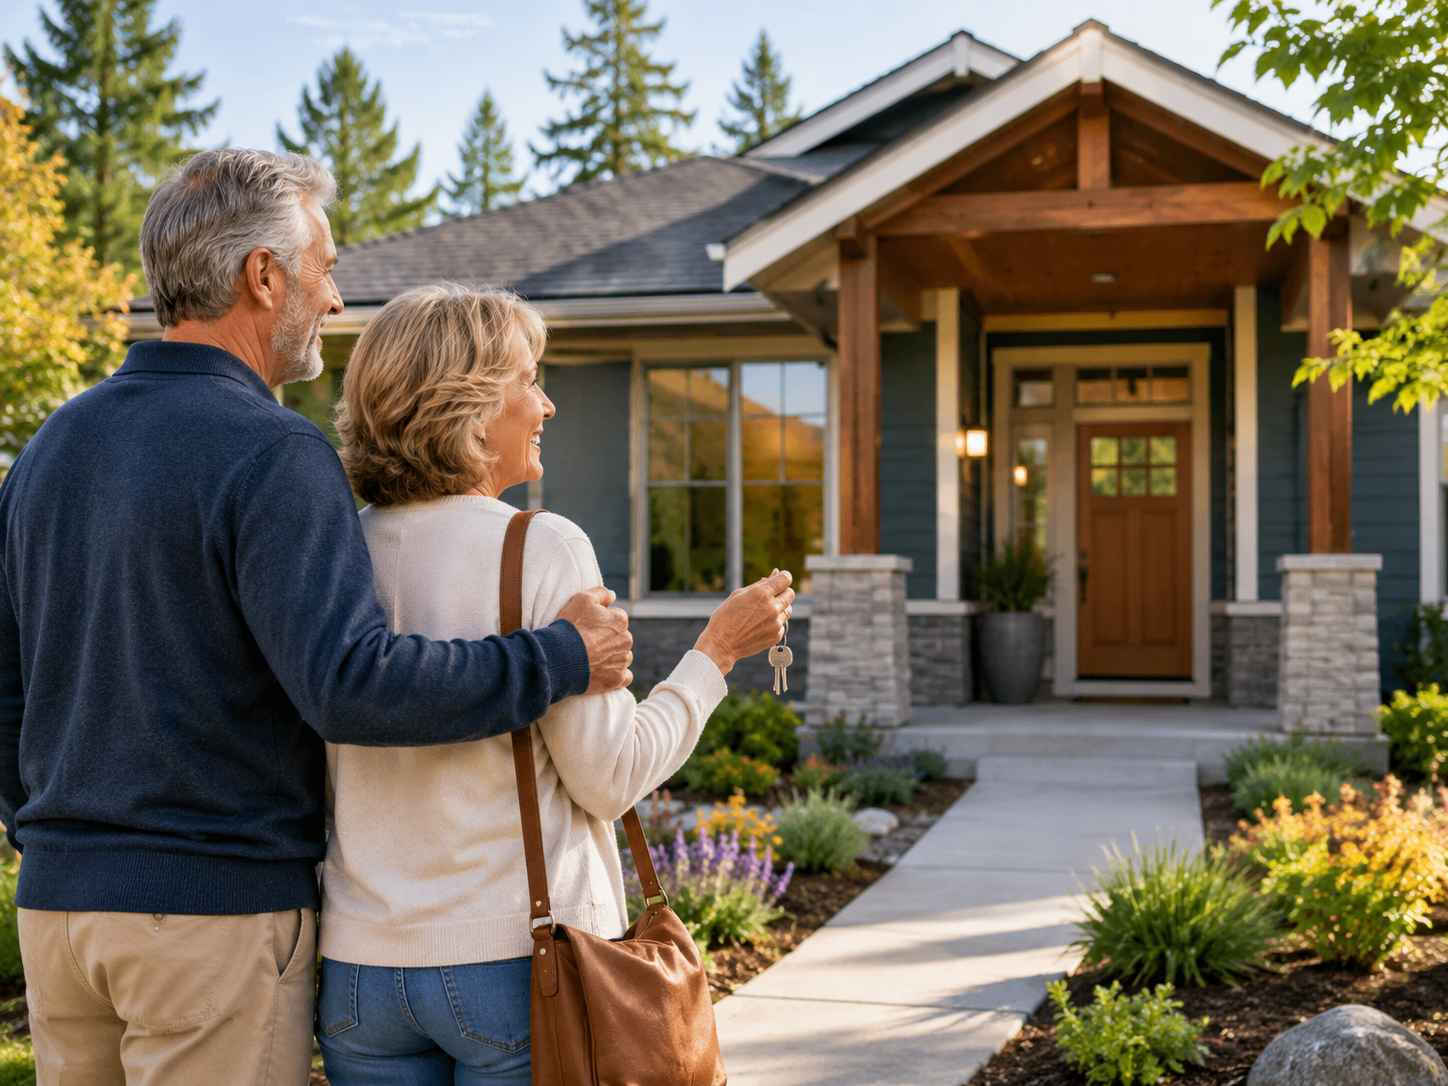
How Does a Reverse Mortgage Purchase Work?
1 — Choose Your New Home
Find the home you want to purchase as your new principal residence.
2 — Combine Your Funds With a Reverse Mortgage
You contribute a portion of the purchase price from your own funds, and the reverse mortgage provides the remaining financing.
3 — Move In Without Required Monthly Principal & Interest Payments
You own the home and remain responsible for property taxes, homeowners insurance, maintenance, and other applicable property charges, but monthly principal and interest payments are not required.
Could a Reverse Mortgage Be Right for Me?
A reverse mortgage isn't right for everyone. But it may be worth exploring if you're looking for ways to make better use of your home equity as part of your retirement plan.
It may be especially useful if you want to:
• Reduce or eliminate required monthly principal and interest mortgage payments
• Create additional financial flexibility in retirement
• Establish access to home equity for future needs
• Remain in your current home longer
• Purchase a home that better fits the next chapter of your life
The Right Answer Depends on Your Situation
How much equity you have, your age, your current mortgage, your future housing plans, and what you want your home equity to accomplish can all affect whether a reverse mortgage makes sense.
That’s why the first step is a conversation—not an application.
Not Sure Whether a Reverse Mortgage Is Right for You?
You don't need to figure it out on your own. We can talk through your goals, your current mortgage and home equity, and the options that may be available—without any obligation to move forward.